 promerget.ai
Travel is consolidating. Just not where most people are looking.
A European travel holding grew its gross revenue from €77 million to €307 million in twelve months.
Seven brands, bought together since 2022. 570 people, more than 25 countries.
In early September it committed to a single booking platform.
I have played this game before. Ten acquisitions, seven brands, five countries, one platform.
That is why I know what this number means: this is not growth. It is buying.
The sequence is always the same. Brand and management stay at first. Finance and operations are merged immediately. The rebrand comes last.
Know this sequence, and you see a consolidation quarters before everyone else.
Now the part almost everyone misreads.
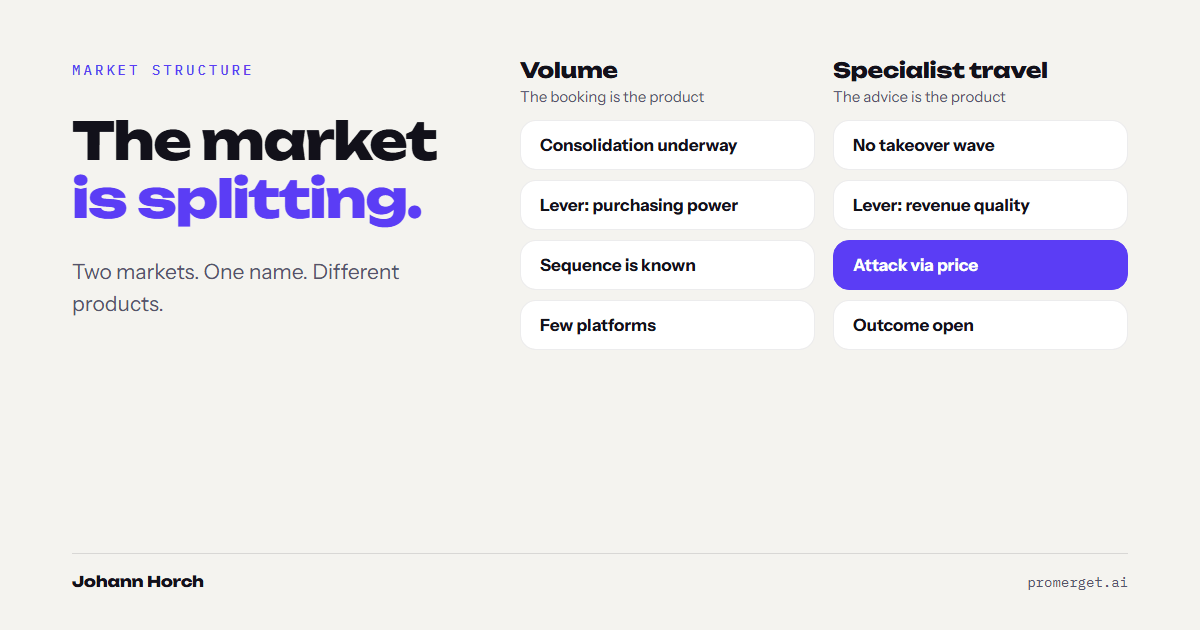
This is not the owner-led specialist travel market. There, people sell advice, not volume. Different product, different customers, different margin.
The volume market lifts its margin through purchasing power. The specialist market lifts it through process. You cannot buy your way to that.
That is why the attack on the owner-led market will not come as a takeover offer.
It will come as a price anchor. Booking technology, native in the agency's own website, nominally free for the agency, paid for through commission and overrides.
Get used to that, and in three years you are no longer negotiating quality. You are negotiating percentages.
The market is splitting right now. Over the coming weeks I will write about which half you want to end up in.